Home Loans & Financing in Malaysia: Guides
For most buyers the housing loan decides what they can buy, so understanding how Malaysian banks lend is as important as choosing the property. The guides in this section explain how a loan is assessed, priced and protected, and what your options are once you already have one.
Banks look first at your debt service ratio (DSR): how much of your monthly income already goes to repaying debts, and how much a new instalment would add. Car loans, personal loans, PTPTN repayments and credit card balances all count. Our DSR guides show how the ratio is calculated, why two banks can reach different answers for the same applicant, and what borrowers do to improve their position, such as clearing smaller debts or applying jointly.
The price of a loan is tied to interest-rate benchmarks. Bank Negara Malaysia sets the Overnight Policy Rate (OPR), and banks price variable-rate home loans against a Standardised Base Rate (SBR) or Base Rate plus a spread. We explain how these fit together, how an OPR change can flow through to your instalment, and the difference between fixed and variable packages. Loan tenure is the other lever: a longer tenure lowers the monthly payment but increases the total interest paid, and our tenure comparison sets out the trade-off.
Protecting the loan is a separate decision. Mortgage reducing term assurance (MRTA) and mortgage level term assurance (MLTA) work differently in cost, coverage and portability, and our guides compare them so you can decide whether the policy offered with the loan is the right one.
There are also routes for specific groups. Civil servants may finance a home through LPPSA, the Skim Jaminan Kredit Perumahan (SJKP) helps borrowers without a fixed monthly income, and first-home schemes can reduce the downpayment needed. We cover eligibility and the application steps for each.
Once you own a home, the guides look at refinancing to a lower rate or releasing equity, the costs involved and how to work out the break-even point, as well as what happens when a bank valuation comes in below the SPA price, when a guarantor is needed and how a joint loan is restructured after a separation.
Rates and lending policies change, so every guide shows when it was published or last reviewed. Confirm current terms with your bank before you sign.
All financing guides(25)
Retrenchment & Home Loan Malaysia: What to Do If You Lose Your Job
What happens to your Malaysian home loan if you're retrenched. Bank moratorium options, EPF Account 2 Account 3 relief, insurance claims, selling vs refinancing, and avoiding foreclosure.
Bank Valuation Lower Than SPA Price? Malaysia 2026 Fixes
Low bank valuation in Malaysia means your loan is based on the valuer's figure, not the SPA price. The cash gap math, why it happens and 5 ways to close it.
EPF Account 3 to Buy a House 2026: Akaun Fleksibel vs Account 2
Yes, you can use EPF Account 3 (Akaun Fleksibel) for a house: withdraw any time from RM50, no SPA needed. How it combines with Account 2 housing withdrawal in 2026.
35-Year vs 30-Year Housing Loan Tenure Malaysia 2026: Interest & DSR
On a RM500,000 loan at 4.0%, 35 years cuts the instalment by RM173 a month but adds about RM70,000 of interest. BNM's 35-year cap, age limits and DSR.
LPPSA Interest Rate 2026: 4% Fixed, Eligibility & Loan Limit
LPPSA charges 4% fixed for the full term, up to 100% financing, 35 years or age 90. 2026 eligibility rules, RM750,000 limit (RM1m announced), 7 loan types.
Full Loan & 100% Financing Schemes Malaysia 2026: Zero Down
How to get a 100% home loan in Malaysia in 2026: SJKP guarantees for gig workers and first-time buyers, LPPSA for civil servants, and the cash you still need.
Guarantor for Housing Loan Malaysia 2026: Rules & Liability
Who can guarantee a Malaysian housing loan, what you are liable for, CCRIS impact, social guarantor bankruptcy protection, and how to be released.
Refinancing Housing Loan to Consolidate High-Interest Debts Malaysia 2026
Debt consolidation refinancing in Malaysia 2026: how cash-out refinancing swaps 18% card debt for a ~4% home loan, the real savings, extra interest and costs.
Stamp Duty Remission for First-Time Homebuyers Malaysia 2026
A complete 2026 legal guide on stamp duty exemptions for first-time homebuyers in Malaysia. Calculate MOT & loan agreement stamp duty savings.
DSR Malaysia: How Banks Decide Your Home Loan Amount
How DSR is calculated for home loans. The formula, bank thresholds 60–70%, and how to improve your DSR before applying.
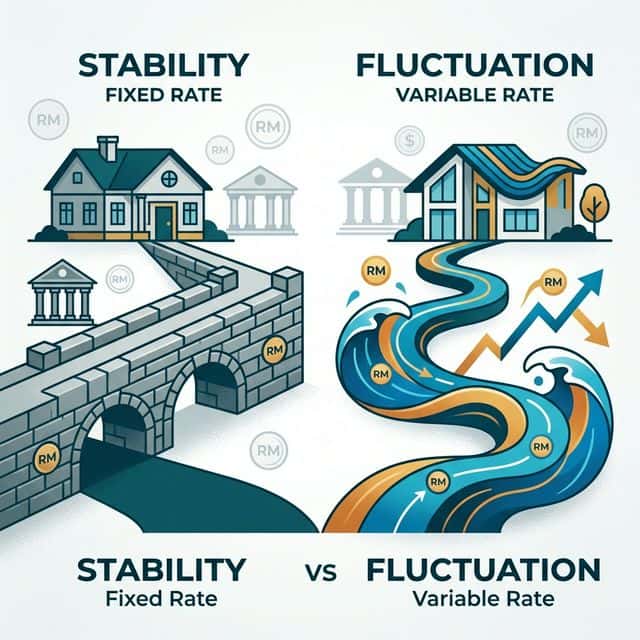
Fixed vs Variable Rate Mortgage Malaysia 2026
Compare fixed and variable rate home loans. Current rates from Maybank, CIMB, RHB, and which suits first-time buyers vs investors.
Home Loan Malaysia 2026: Complete Housing Loan Guide
Compare home loans in Malaysia 2026. SBR rates, fixed vs variable, Islamic financing, DSR, EPF usage, and how to choose the best bank.
MRTA vs MLTA 2026: Which Mortgage Insurance to Choose
MRTA cover shrinks with your loan and pays the bank; MLTA stays level and moves with you. Coverage, cost on a RM500K loan, takaful and term life compared.
OPR Malaysia 2026: Current Rate & Home Loan Impact
Malaysia's OPR for 2026. Current rate, BNM meeting schedule, OPR history, and how changes affect your monthly repayment.
SBR vs BR vs BLR Malaysia: Home Loan Rates Explained
SBR, BR, and BLR in Malaysia. How Standard Base Rate works, OPR connection, impact on home loan repayment, what to compare.
MLTA Insurance Malaysia 2026: Coverage, Cost & How to Buy
MLTA insurance in Malaysia explained: how Mortgage Level Term Assurance works, 2026 cost estimates, critical illness riders, tax relief, and how to buy bank-bundled vs standalone.
Joint Loan vs Single Name Mortgage Malaysia 2026: DSR & Eligibility
Joint vs single-name home loans in Malaysia: combined DSR, first-time stamp duty quota, joint liability, and how to refinance a joint loan into one name.
MRTT vs MLTT Takaful Mortgage Insurance Malaysia 2026: Math
A financial 2026 comparison of MRTT vs MLTT Takaful mortgage insurance in Malaysia. Calculate premiums, cash values & Takaful protection.
Housing Credit Guarantee Scheme (SJKP) Malaysia: 2026 Guide
A complete guide to the Housing Credit Guarantee Scheme (SJKP) Malaysia 2026. Learn about SJKP eligibility, 120% financing, and how it helps gig workers buy homes.
How to Remove a Joint Borrower from Housing Loan Malaysia 2026
A complete 2026 financial guide on removing a co-borrower or spouse from a joint housing loan in Malaysia. Calculate single DSR & refinancing steps.
Budget 2026 Malaysia Property: 8% Foreign Stamp Duty & More
From 1 Jan 2026 foreigners pay a flat 8% stamp duty on residential transfers, up from 4%. The first-home exemption up to RM500,000 runs to 31 Dec 2027.
Housing Loan Lock-In Period & Early Settlement Penalty Malaysia 2026
A complete 2026 financial guide on housing loan lock-in periods in Malaysia. Calculate early settlement penalty fees, clawback clauses & start dates.
Housing Loans & DSR: Can You Actually Afford That House?
How Malaysian banks approve housing loans in 2026: the DSR formula, how much you can borrow on your income, Flexi vs Term loans and margin of finance rules.
Housing Loan Early Settlement & Principal Payoff Malaysia 2026
A complete 2026 guide on early settlement of housing loans in Malaysia. Calculate interest savings, lump-sum principal payoffs & redemption fees.
Downpayment Guide: How Much Do You Really Need? (2026)
How much downpayment you need for a Malaysian home in 2026: 10% on a first or second housing loan, 30% from the third, plus 4-5% for legal fees and stamp duty.